A direct trustee-to-trustee gold IRA transfer often completes in days to two weeks, which makes it the fastest route available. Indirect rollovers invoke the IRS 60 day clock and commonly take longer once withholding and paperwork delays are factored in. End to end, from opening a self-directed account to confirmed storage, most rollovers finish in roughly two to four weeks.
TL;DR:
- A new account typically takes 2 to 5 business days to open; prepare identification, beneficiary details, and current statements before applying.
- Employer plan requests often take 1 to 2 weeks, and batch processing, employer approval, or monthly distribution dates can add further delays.
- If you receive funds directly, deposit the full distribution within 60 days; employer plans may withhold 20%, which you must replace from other funds.
- Missing signatures, outdated account numbers, or name mismatches can send paperwork back for correction and add a week or more.
- Rare or high demand metals can take a week or longer to source, so naming acceptable alternatives before purchase can keep settlement moving.
Table of Contents
- Stage-by-Stage Timeline From Account Opening to Storage
- Direct Vs Indirect Rollovers: Timing, Withholding, and Risk
- IRS Rules That Control How Fast You Can Move
- What Actually Causes Delays, and How to Avoid Them
- A Step-by-Step Checklist to Move Faster
- How an In-House IRA Team Helps You Avoid Delays
- When to Start Your Rollover and What Buffer to Build In
- Start Your Rollover With Our In-House Team
- FAQ
- Sources
Stage-by-Stage Timeline From Account Opening to Storage
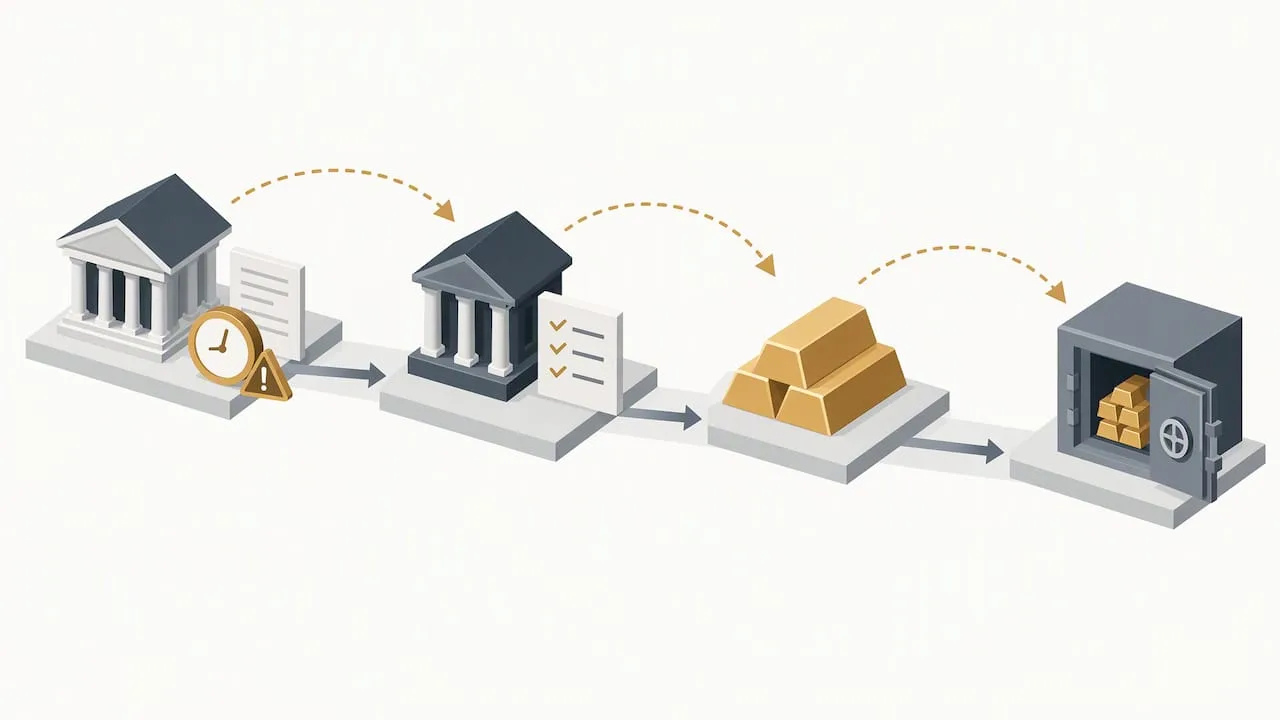
A gold IRA rollover moves through five distinct stages, and each one has its own realistic timing window. Knowing what happens at each stage helps you spot delays before they stack up.
1. Opening the self-directed IRA. Before any funds move, you need a self-directed IRA account set up with a qualified custodian. This typically takes 2 to 5 business days once you submit identification, a completed application, and beneficiary designation forms. Have these ready:
- A government-issued photo ID for identity verification.
- Current statements from the retirement account you plan to move.
- Beneficiary names and dates of birth for the new account.
- A copy of your former plan’s distribution or transfer request form.
2. Initiating the transfer or rollover request. This is where timing varies the most. A direct trustee-to-trustee transfer from an existing IRA custodian often moves in a matter of days because the two institutions deal directly with each other. Requests tied to an employer plan, such as a 401(k), tend to run 1 to 2 weeks because plan administrators have their own processing calendars, approval chains, and sometimes require notarized forms or employer sign-off. Some plans only process distribution requests on specific dates each month, which can add unplanned waiting time.
3. Custodian processing on receipt. Once the sending institution releases the funds, the receiving custodian verifies the transfer, confirms the amount matches what was expected, and posts it to your new account. Wire transfers often clear within 1 to 3 business days. Checks mailed between institutions add several more days for mail transit and bank holds before funds are available to spend.
4. Metals purchase and settlement. With funds posted, you select the gold, silver, platinum, or palladium products for the account. Common bullion coins and bars that are in regular stock can settle within days. Less common products, or high-demand items during periods of strong market activity, may carry sourcing or backorder lead time that pushes settlement out by a week or more. Specifying acceptable alternate products upfront keeps this stage from stalling.
5. Storage assignment and final confirmation. Once metals are purchased, the depository assigns storage and the custodian issues a confirmation statement showing exactly what you own and where it is held. This final confirmation typically arrives within a few business days of settlement, giving you a complete paper trail from distribution to stored asset.
Each stage depends on the one before it, so a delay early in the process (a slow-moving plan administrator, for example) carries forward through everything that follows.
Direct Vs Indirect Rollovers: Timing, Withholding, and Risk
The method you choose to move retirement funds has more effect on your timeline than almost any other factor. Direct and indirect rollovers reach the same destination, but they get there very differently.
A direct transfer moves money from one custodian to another without ever passing through your hands. You never receive a check or a cash distribution, so there’s no 60-day clock and no mandatory withholding to worry about. This is why it’s usually the fastest and lowest-risk option, and why custodians generally recommend it as the default choice. You request it by asking your current IRA custodian or plan administrator to send funds or assets directly to your new self-directed IRA custodian, naming the receiving account on the paperwork.
An indirect rollover works differently. The distribution is paid to you first, and you then have 60 days from the date you receive it to deposit the full amount into a new eligible retirement account, a rule set directly by the IRS. Miss that window and the distribution can become taxable, and potentially subject to an early withdrawal penalty if you’re under 59 and a half.
Indirect rollovers carry one more complication: distributions from employer plans are generally subject to mandatory 20% federal withholding, as described in IRS Publication 575. That means if you want to roll over the entire original balance, you have to come up with the withheld 20% from other funds and complete the rollover within 60 days, then claim the withheld amount back when you file taxes.
- Direct transfers: no 60-day deadline, no mandatory withholding, generally the fastest path.
- Indirect rollovers: 60-day deadline applies, 20% withholding often applies, and replacing those funds can extend the practical timeline by days or weeks.
- Indirect rollovers are sometimes unavoidable with certain plan types or when a plan only issues checks payable to the account holder rather than to a new custodian.
Our guide to rollovers versus transfers walks through how to tell which process your current plan will use before you start.
IRS Rules That Control How Fast You Can Move
The 60-day rule is the single most important deadline in this process. The IRS states that once you receive an eligible distribution, you generally have 60 days to deposit it into another eligible retirement plan or IRA to preserve its tax-deferred status. Trustee-to-trustee transfers never start this clock because the funds never pass through your hands.
Withholding adds a layer most people don’t anticipate. Under the rules in Publication 575, many distributions from employer plans are subject to mandatory withholding, which means the check you receive is already short by that amount even though you’re expected to roll over the full original balance.
One in-market figure worth knowing: industry reporting on gold IRA setups found that a typical rollover completes within about two to four weeks end-to-end, with direct transfers generally landing at the faster end of that range.
The IRS does allow limited exceptions to the 60-day rule in specific circumstances, including certain automatic waivers and situations described in published revenue procedures, but these are narrow and documented directly on IRS.gov rather than through informal extensions. Reporting also enters the timeline here: a distribution typically generates a Form 1099-R from the paying institution, and your new custodian issues its own statements once the rollover completes, creating the documentation trail you’ll want on hand at tax time.
- The 60-day rule starts on the date you receive the distribution, not the date it was requested.
- Mandatory 20% withholding applies to many employer plan distributions, not to direct trustee-to-trustee transfers.
- Narrow waiver provisions exist but require specific qualifying circumstances documented through IRS guidance.
- Form 1099-R and custodian year-end statements are the standard reporting documents tied to a completed rollover.
Our breakdown of how to stop 20% withholding during a 60-day rollover covers the mechanics in more detail.
What Actually Causes Delays, and How to Avoid Them
Most rollovers that run long aren’t stuck because of the custodian receiving the metals IRA. They’re stuck earlier, usually at the former plan administrator or in a paperwork detail that gets caught in review.
Employer plans are the single biggest source of delay. Many 401(k) administrators process distribution requests on a batch schedule rather than on demand, and some require your employer’s HR or benefits team to sign off before the request even reaches the plan’s recordkeeper. Calling ahead to ask about the plan’s specific processing calendar, and submitting your request as early as possible, gives you a real shot at the faster end of the timeline.
Paperwork errors are the second-biggest cause. A missing signature, an outdated account number, or a name mismatch between your ID and your account registration can bounce a request back for correction, costing a week or more. Before submitting anything:
- Confirm the receiving custodian’s exact account number and registration name.
- Check that every required signature line is completed, including spousal consent where applicable.
- Verify your current mailing address matches what’s on file with both institutions.
- Ask the former plan administrator directly whether they prefer a direct transfer or will only issue a distribution check.
Custodian holds are usually procedural rather than arbitrary. Ask upfront what triggers a hold on a given custodian’s calendar, whether that’s identity verification, a minimum processing window for new accounts, or a check-clearing period for mailed funds.
Metal sourcing can also add time if you’re set on a specific product during a period of high demand. Specifying acceptable alternate coins or bars of the same metal and purity ahead of time keeps a purchase from stalling while you wait for one exact product to come back in stock.
Pro Tip: Ask your former plan administrator for their average processing time in writing before you submit anything, and use that figure to set your own expectations for the rest of the timeline.
A Step-by-Step Checklist to Move Faster
Hitting the fast end of the timeline comes down to preparation and documentation. Follow these steps in order:
- Gather your identification, most recent account statements, and beneficiary information before contacting any institution.
- Open your self-directed IRA account with your chosen custodian and confirm the exact account number you’ll give to the sending institution.
- Contact your former plan administrator and specifically request a trustee-to-trustee transfer rather than a distribution check, naming your new custodian and account number directly on the form.
- Ask the former administrator for their typical processing time and get that estimate in writing if possible.
- Once funds arrive, confirm receipt with your new custodian and get a written expected date for metals settlement.
- Select metals products, including acceptable alternates, to avoid delays from sourcing a single specific coin or bar.
- Request written confirmation of the settlement date and the storage facility assignment once the purchase completes.
- If 20% withholding occurred because the distribution came to you directly, plan to replace that withheld amount from other funds so the full original balance is rolled over within the 60-day window.
Our step-by-step paperwork checklist lists the exact forms most custodians require, and our rollover timeline checklist walks through the same steps with space to track your own dates.
How an In-House IRA Team Helps You Avoid Delays
We built our IRA department to focus on critical parts of this process such as paperwork accuracy, plan administrator follow-up, and metals sourcing. Our team assists in preparing transfer paperwork, confirming account details with the sending institution, and following up directly to help avoid delays.
- Trustee-to-trustee transfers are generally requested to avoid the 60-day deadline and withholding.
- Inventory management and acceptable alternates across gold, silver, platinum, and palladium products are maintained to help reduce sourcing wait time.
- Our insured private delivery service tracks your shipment from settlement to confirmed receipt.
Pro Tip: Ask our IRA team for a written estimate of your expected completion date before you submit any transfer paperwork, so you know exactly what to expect at each stage.
Request a Free Precious Metals Consultation. Call (888) 859-0978 to talk through your specific plan type and timeline before you start. This article is educational and general in nature, not personalized investment, tax, or legal advice.
When to Start Your Rollover and What Buffer to Build In
Start earlier than you think you need to. If a required distribution date, retirement date, or other deadline is on the calendar, give yourself a full month of buffer rather than assuming the fastest timeline applies to your situation.
Watch for employer plan slowdowns around year-end and any announced plan freeze or blackout periods, both of which can stretch an otherwise routine request. Choose a direct transfer whenever your plan allows it, and ask every institution involved for written confirmation of dates rather than relying on verbal estimates.
— Blake
Start Your Rollover With Our In-House Team
Moving a retirement account into physical metals doesn’t have to mean chasing down paperwork or guessing at processing times. Our in-house IRA department handles the transfer request, confirms every document before it’s submitted, and keeps you updated at each stage from account opening through insured delivery or depository storage. We work directly with your current custodian or plan administrator to request a trustee-to-trustee transfer whenever possible, which keeps your rollover off the 60-day clock entirely.
Request a Free Precious Metals Consultation. Call (888) 859-0978, or start the process now by visiting our IRA account opening page to see what documents you’ll need for your specific plan type.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can an IRA be rolled into gold?
Yes, a traditional or Roth IRA can be rolled into a self-directed IRA that holds physical gold, silver, platinum, or palladium meeting IRS purity standards. The process typically uses a trustee-to-trustee transfer to move funds from your existing custodian into the new self-directed account before any metals are purchased.
How long does it take for a rollover IRA to process?
Processing time depends heavily on the method and the institutions involved. A direct trustee-to-trustee transfer often completes within days to two weeks, while a full rollover involving an employer plan and a new metals purchase commonly takes two to four weeks end-to-end.
What is the 60 day rule for IRA rollovers?
The IRS 60-day rule requires that once you personally receive a retirement account distribution, you must deposit the full amount into another eligible retirement account within 60 days to preserve its tax-deferred status. This rule only applies to indirect rollovers, since direct trustee-to-trustee transfers never put the funds in your hands.
What is the downside of a gold IRA?
Self-directed IRAs holding physical metals carry fraud and liquidity risks that FINRA and the SEC have specifically flagged, which is why verifying custody, storage, and fee arrangements in writing matters before you commit funds. Costs and timing can also be affected by how a plan administrator processes your request, so confirming expectations upfront helps avoid surprises.
Sources
- Investor Alert: Self-Directed IRAs and the Risk of Fraud | FINRA
- Gold IRA timeline: How long setup takes and what can slow it down | CBS News