
Yes, you can move a 401(k) into gold without owing taxes or penalties, and the safest way is a direct, custodian-to-custodian rollover into a self-directed Gold IRA. An indirect rollover works too, but only if you redeposit the full amount within 60 days. The two costliest mistakes are taking personal possession of the metal and missing that 60-day window, both of which the IRS treats as a taxable distribution.
TL;DR:
- A direct custodian-to-custodian rollover into a self-directed Gold IRA is the safest way to transfer a 401(k) into gold without taxes or penalties, avoiding the 60-day window risk.
- Ensure a Gold IRA is established first with an IRS-approved custodian and confirm transfer details before moving funds to prevent misclassification as a taxable distribution.
- Only IRS-approved gold products with at least 99.5% fineness and stored in an qualified depository qualify for a gold IRA, with physical possession considered a taxable event.
- An indirect rollover involves a 20% withholding and requires redepositing the full amount within 60 days to avoid taxes and penalties, making it riskier than a direct transfer.
- Using a dedicated service like GoldRock Metal Exchange can help coordinate paperwork, confirm transfer details, and avoid errors that could trigger taxes or disqualify the rollover.
Table of Contents
- Steps to Roll a 401(k) Into Gold Without a Penalty
- Direct Rollover vs. Indirect Rollover: What Actually Changes at Tax Time
- What Gold Qualifies for an IRA, and Where It Has to Live
- When Does a Rollover Become a Taxable Event?
- Timing Rules and Plan-Specific Limits to Check First
- Is Adding Gold to a Retirement Account Worth the Cost?
- Red Flags That Signal a Prohibited Transaction or Fraud
- How GoldRock Metal Exchange Helps With a Compliant Rollover
- A Straight Answer on Timing
- Get Help Rolling Over Without the Guesswork
- Sources
- FAQ
Steps to Roll a 401(k) Into Gold Without a Penalty
Moving retirement money into physical metal isn’t complicated, but the order of operations matters. Skip a step or get the paperwork wrong, and the IRS can reclassify the whole transaction as a distribution.
-
Open a self-directed Gold IRA first. You need this account established before any money moves. A regular IRA custodian can’t hold physical bullion, so you need one that specializes in self-directed IRAs and works with an approved depository. The custodian’s job is to hold title to the metal, file the required IRS reporting, and keep the account structured correctly. Skipping this step, or picking a custodian that isn’t set up for precious metals, is the single most common reason rollovers stall.
-
Request a direct rollover from your 401(k) administrator. Call your plan’s administrator and ask specifically for a “direct rollover” or “trustee-to-trustee transfer,” not a distribution. You’ll typically need to provide your new custodian’s name, account number, and mailing instructions for the check or wire. Ask for this in writing, and get a confirmation number for the request.
-
If the plan refuses a direct transfer, use the indirect method carefully. Some older plans or specific plan types only issue distributions payable to you. If that happens, the plan will withhold 20% for federal taxes automatically, and you’ll need to make up that difference out of pocket to complete a full, tax-free rollover within 60 days.
-
Purchase IRS-approved gold once funds land in the new IRA. Your custodian will confirm the funds arrived, and only then can you direct a purchase of eligible bullion or coins. The metal ships directly to an approved depository. It never touches your hands.
-
Collect and keep every piece of paperwork. Save the transfer confirmation from both custodians, the depository’s storage receipt, and any Form 1099-R your former plan issues (this form gets filed even on tax-free rollovers, coded to show no tax is due).
Two things trip up otherwise careful investors: mismatched account names between custodians and rollover checks made payable to the individual instead of the new custodian. Both can force a taxable distribution even when the intent was a clean transfer.
Pro Tip: Ask your new custodian for a written “letter of acceptance” before you contact your 401(k) administrator. Some plans require proof that a qualified receiving account exists before they’ll release funds, and having it ready can shave days off the process.
Direct Rollover vs. Indirect Rollover: What Actually Changes at Tax Time
The mechanics here decide whether your rollover is a non-event on your tax return or a scramble to avoid a big tax bill.
A direct rollover moves money custodian-to-custodian. You never receive a check, so there’s no mandatory withholding and nothing to report as income. A direct transfer generally does not trigger an immediate tax bill when the paperwork correctly identifies both accounts.
An indirect rollover works differently. Your plan cuts you a check, but withholds 20% for federal taxes before you see it. That creates a real cash problem:
- You receive a partial amount from a distribution due to withholding.
- To complete a tax-free rollover, you must deposit the full original distribution amount into your Gold IRA within 60 days, which may require covering any withheld portion out of your own pocket.
- You get the withheld amount back only when you file your tax return, so the shortfall sits on you for months.
If you miss the 60-day deadline or can’t cover the withheld amount, the IRS treats the shortfall as a taxable distribution, and if you’re under 59½, a 10% early withdrawal penalty applies on top of ordinary income tax.
Why anyone chooses indirect rollovers anyway: some plans simply won’t do direct transfers to certain custodians, or you’re consolidating multiple old accounts and want a short window of access to the cash. It’s a legitimate path, just a riskier one that leaves no room for error.

What Gold Qualifies for an IRA, and Where It Has to Live
Not every gold product is eligible, and the storage rules are stricter than most new investors expect.
The IRS requires IRA-held gold to meet a minimum fineness standard of 99.5%, with similar purity thresholds set for silver, platinum, and palladium. This is why generic “gold coins” or collectible numismatic pieces are usually disallowed. Eligible products generally include specific government-minted bullion coins and bars produced by accredited refiners.
Custody is the other non-negotiable piece. The IRS requires IRA assets, including precious metals, to be held by a qualified trustee or custodian, not by the account owner. That means:
- No home storage, no personal safe, no safety deposit box in your own name.
- Metal must sit in an approved depository or with a qualified non-bank trustee.
- Taking physical possession of IRA-owned gold, even briefly, is treated as a taxable distribution.
Before committing to a custodian, ask for proof of the depository’s insurance coverage and its most recent audit report. Reputable operators provide these documents without hesitation, and reviewing them takes only a few minutes.
When Does a Rollover Become a Taxable Event?
A rollover stays tax-free as long as the money moves correctly and stays inside the IRA structure. It becomes taxable the moment one of a few specific things goes wrong.
The most common triggers are a missed 60-day deadline on an indirect rollover, a prohibited transaction (using IRA assets for personal benefit), or taking physical possession of IRA-owned metal. Each of these causes the IRS to reclassify the transaction as a distribution rather than a transfer.
If you’re under 59½ when that happens, you owe ordinary income tax on the full amount plus a 10% early withdrawal penalty. Missing the rollover deadline is one of the costliest and most preventable mistakes investors make, and the remedies afterward are limited.
Your former plan reports the distribution on Form 1099-R regardless of whether the rollover was direct or indirect. On a properly executed direct rollover, the form is coded to show no tax is due. Keep that form along with your custodian’s transfer confirmation and depository receipt. If the IRS ever questions the transaction, this paper trail is what proves it was a rollover, not a cash-out.
If you do miss the window, there’s a narrow IRS process for requesting a waiver in cases of illness, postal error, or certain other circumstances, but approval isn’t guaranteed. This is exactly the kind of situation where a tax professional’s guidance is worth the cost of the consultation.
Timing Rules and Plan-Specific Limits to Check First
Not every dollar in a 401(k) is automatically eligible to roll over, and plan rules vary more than most people assume.
Required minimum distributions can’t be rolled into an IRA. Hardship withdrawals and certain other plan-specific payouts generally aren’t eligible either. And some employer plans restrict rollovers entirely while you’re still actively employed, sometimes called an “in-service” restriction.
Before you initiate anything, confirm:
- Whether your plan allows in-service rollovers if you’re still working for the employer.
- Whether any portion of your balance is subject to an RMD that year.
- Your plan administrator’s specific paperwork requirements and processing timeline.
A five-minute call to your plan administrator before starting the process can save weeks of back-and-forth later.
Is Adding Gold to a Retirement Account Worth the Cost?
Investors typically add gold for diversification, as a counterweight to stocks and bonds rather than as a growth engine. There’s no guarantee of appreciation, and gold’s price moves independently of, and sometimes against, the rest of a portfolio.
The costs are real and worth budgeting for: custodian setup and annual fees, depository storage fees, and dealer markups over the metal’s spot price. These add up over time and eat into net returns, so it pays to understand the full fee schedule before you commit funds.
On allocation, financial commentators commonly suggest limiting gold to a modest slice of a retirement portfolio, often in the 5% to 10% range, rather than concentrating retirement savings in a single metal.
Pro Tip: A Gold IRA generally makes more sense than an ETF when your goal is owning the physical metal itself, with direct custody and insured storage. If you just want price exposure without the storage and custodian fees, that’s a different conversation, and one worth having with a financial advisor before you roll anything over.
Red Flags That Signal a Prohibited Transaction or Fraud
A few warning signs separate a legitimate rollover from a costly mistake or a scam.
- Self-dealing: using IRA funds to buy metal from yourself, a family member, or a business you control is a prohibited transaction under IRS rules.
- “Just hold it at home for now” suggestions: any custodian or dealer who suggests you can store IRA metal personally, even temporarily, is steering you toward a taxable distribution.
- Pressure to move fast: legitimate rollovers take time for paperwork and verification; urgency is a common fraud tactic.
- Unwillingness to provide documentation: a real custodian or depository will readily share insurance certificates, audit reports, and fee schedules on request.
Before you commit, verify a custodian’s registration and check for Department of Labor fiduciary guidance on what standards apply, and confirm the depository’s credentials independently rather than taking a single dealer’s word for it.
How GoldRock Metal Exchange Helps With a Compliant Rollover
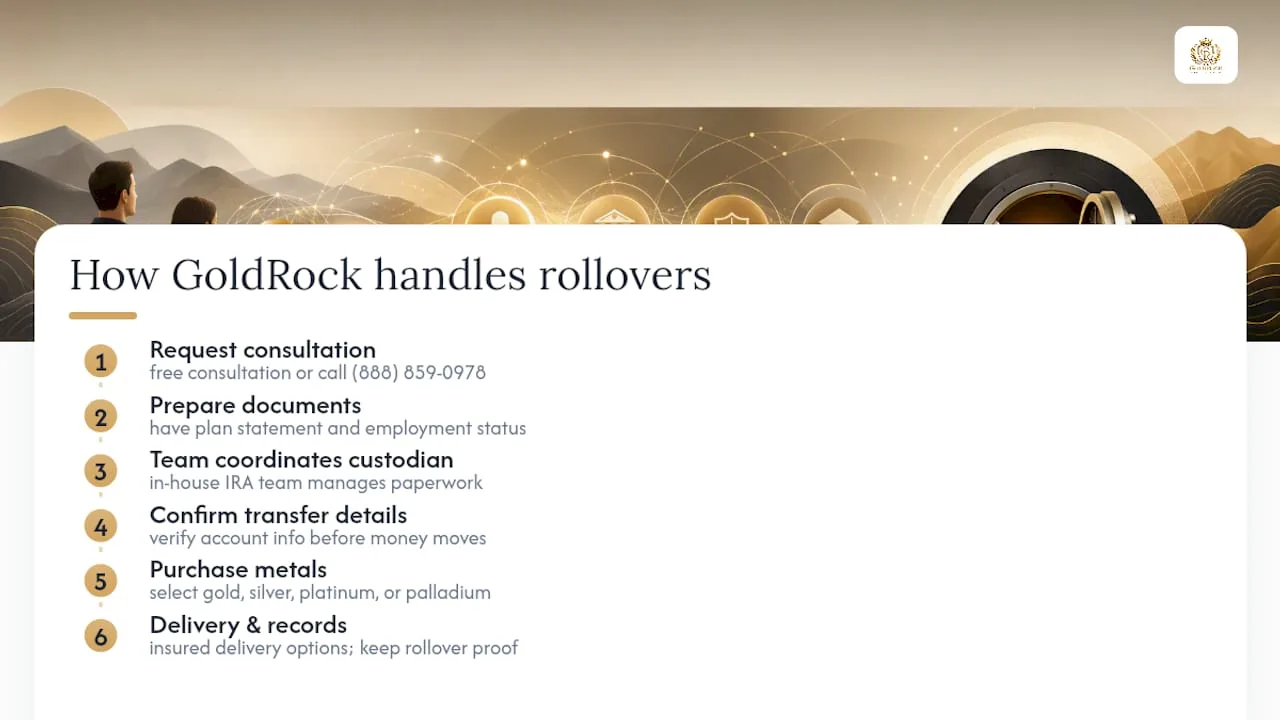
Paperwork accuracy is what makes or breaks a penalty-free rollover, and it’s where most delays and errors happen. GoldRock Metal Exchange runs a dedicated in-house IRA department built specifically to coordinate that process: working directly with your chosen custodian, confirming transfer details before funds move, and helping you assemble the documentation that proves a clean rollover if the IRS ever asks.
Once your Gold IRA is funded and metal is purchased, GoldRock also offers insured private delivery for any personal (non-IRA) purchases you make outside the retirement account, so you’re covered whether the metal goes to an approved depository or to you directly.
A few things worth having ready before you call:
- Your current 401(k) statement, showing balance and administrator contact information.
- Whether you’re still actively employed with the plan sponsor.
- A rough sense of how much you’d want allocated to physical metal versus other IRA assets.
If you want a second set of eyes on the process before you start, request a free precious metals consultation and walk through your specific situation with someone who does this daily.
A Straight Answer on Timing
The safest move is almost always the boring one: request a direct, custodian-to-custodian transfer, get it in writing, and confirm both sides of the transaction before funds move. Indirect rollovers can work, but they add a 60-day clock and a cash-flow trap most people don’t see coming until the check is already in their hands. None of this replaces a conversation with a tax advisor about your specific plan, your age, and your broader retirement picture. Treat the paperwork as the whole job, not a formality, and the rest tends to go smoothly.
— Blake
Get Help Rolling Over Without the Guesswork
GoldRock Metal Exchange gives you what a generic custodian search doesn’t: a dedicated in-house IRA team that handles the custodian coordination directly, so you’re not the one chasing paperwork between two institutions.
That matters most in the exact spots where rollovers go sideways, mismatched account details, missed transfer windows, or unclear documentation once tax season arrives. A dedicated team can work the transfer with your new custodian, confirm the details before money moves, and help you keep the records that prove the rollover was done right. Once metal is purchased, insured private delivery may be available for purchases outside the IRA structure.
If you’re ready to talk through your specific 401(k) situation, request a free precious metals consultation or call (888) 859-0978. Have your plan statement and employment status on hand. From there, GoldRock can walk you through what a compliant, penalty-free transfer looks like for your account, including which gold, silver, platinum, or palladium products fit your goals.
This article provides general educational information and is not personalized investment, tax, and or legal advice. Consult a qualified tax or financial professional about your specific circumstances.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Rollovers of retirement plan and IRA distributions | IRS
- Step-by-step guide for rolling a 401(k) over to a gold IRA | Fortune
- How to Move Money From Your 401(k) Into Gold | Money
- Rolling over a 401(k) to gold? What to check before you move your money – CBS News
FAQ
Can I use my 401(k) to invest in gold?
Yes. You can roll eligible 401(k) funds into a self-directed Gold IRA through a direct or indirect rollover, provided the transfer follows IRS custody and timing rules.
Why does Dave Ramsey say not to invest in gold?
Ramsey-style criticism typically centers on gold’s lack of dividends or interest income and its unpredictable price swings compared to stocks. Most advisors who accept some gold allocation still limit it to a small portion of a portfolio, often 5% to 10%, rather than a core holding.
What if I invested $10,000 in gold 20 years ago?
Gold’s price has moved through both extended gains and multiyear stretches of stagnation over the past two decades, and past performance never guarantees future results. Nobody can promise what a similar investment would return going forward.
How many Americans have $1,000,000 in their 401(k)?
The share of 401(k) accounts reaching seven figures is a small minority of all accounts nationally, concentrated among long-tenured savers with decades of consistent contributions. Exact figures vary by plan provider and year, so check your own plan statements for your specific balance and trajectory.
Is there a penalty for rolling a 401(k) into a Gold IRA?
Not when it’s done correctly. A direct rollover avoids withholding entirely, and an indirect rollover stays penalty-free as long as the full amount is redeposited within 60 days.